Updated every Monday!   Subscribe to free weekly newsletter.

Get Your FICO Credit Score Free?

Taking a page from companies advertising free credit reports, a number of firms are now promoting free credit scores, including the company that invented the FICO score:

No disclaimers in the ad.  Nothing.  Maybe it’s really totally free!

When you click the ad, you are taken to this page on the MyFICO site:

Still no obvious strings. No asterisk after the word “free”. Go ahead and click the picture to see it full size. There, on the bottom is the VERY small disclaimer that reads:

*MOUSE PRINT:
 

IMPORTANT INFORMATION: When you order your free FICO Score here, you will begin your 10-day trial membership in Score Watch®. If you don’t cancel your membership within the 10-day trial period, you will be billed $14.95 for each month that you continue your membership. You may cancel your trial membership anytime within the trial period without charge.

The free score is only free when you sign up for a free trial, and if you fail to cancel that free trial within a short 10-days, you will be billed $14.95 monthly.

If you missed that inconspicuous disclosure and click to get your free score, you will be asked to part with a lot of personal information, including your date of birth, social security number, password, and full name and address — all before you are told on a subsequent page that you have to give a credit card number and it will be dinged $14.95 a month if you don’t cancel quickly.

FreeCreditReport.com got better about disclosure after the FTC went after them. And a new consumer law, the CARD Act requires better disclosure in ads promising free credit reports where you are really signing up for a trial of a continuing service. The law does not explicitly extend to offers of free credit scores, however. And therein lies the problem. Though general consumer law would require better disclosure, not until enough complaints get filed against “free score” offers, will disclosure likely improve.
Updated every Monday!   Subscribe to free weekly newsletter.

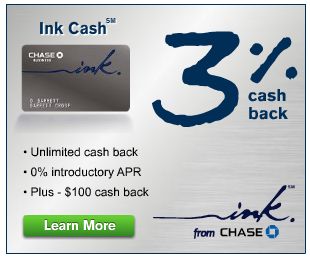
Chase Ink Card: Get 3% Back?

There are many credit cards out there offering a 1% rebate on purchases. And there are just a couple that pay you back 2% on everything. Now, imagine getting a business credit card that rebates 3% on all your purchases, with no cash back limit! Wow.

Keep imagining. At the bottom of Chase’s full screen ad (which you see after clicking “learn more”) is a not particularly conspicuous link labeled “*Ink Offer Details”. Funny, there was no asterisk in their headline qualifying their 3% claim.

*MOUSE PRINT:

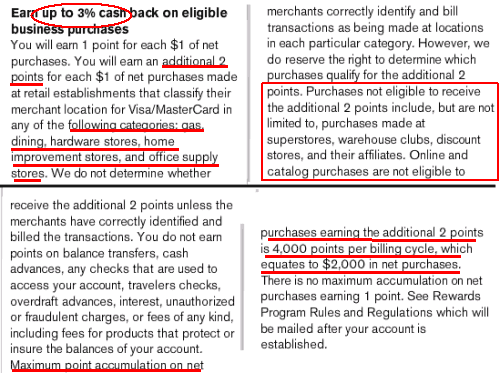
So, the real deal is that you only get 3% back in selected categories (gas, hardware, home improvement, dining, and office supply stores). Otherwise, this is really just a 1% card. And they seem to exclude superstores, discount stores, and warehouse clubs. Hmm, isn’t Home Depot a superstore or discount home improvement store?

And as to the claim that you get “unlimited cash back”, in fact they will limit your extra cash back in the 3% categories to just an extra $40 a month.

So what appeared to be a credit card offering a flat 3% back with no cash back limits, is nothing of the sort.

Mouse Print* pointed out to Chase the potentially misleading nature of their advertisement and asked, “Will Chase revise its advertisements to more accurately say “up to 3% cash back” and qualify its “unlimited cash back” claim?”

Chase replied:

“We are committed to being straightforward in all of our advertising and customer communications. The small banner ad that you are referring to for Ink Cash is referring to the 3% cash back in specific categories and [sic] the then the unlimited cash back for the 1% on everything else.

Our team is reviewing the copy now and although limited by the small space on the banner ad itself, wants to ensure that all applicants fully understand the true value of the card and rewards.” –Chase spokesperson

Trying to cut through the “spin”, Mouse Print* replied to Chase: “There is PLENTY of room to add ‘up to’ in that ad! The question is ‘will you’?”

The company wrote back:

“Up to” is not accurate, though. Customers earn the full 3% on their spending in the select categories, so it’s not an “up-to” and then they earn a full 1% on everything else from the first dollar they spend. We will do our best to make sure that it is more clear.

I could have replied that “up to 3%” is absolutely accurate for the ad they published because there is no mention whatsoever in it about that rate only applying to certain categories. I resisted, and will just leave it to the reader to imagine whether Chase is really inclined to fix their ad.

One other word about the email exchange with Chase. Attached to one of the emails from Chase, clearly by mistake, was a document listing the times over the past several years that I was quoted in major media. It listed the full text of these articles including ones from local television, Chicago Tribune, Fox Business, Associated Press, Washington Post, New York Daily News, etc. Nice to know that Chase PR folks do a little investigation into the reporters or editors who pose questions to them before they respond.