Last week’s biggest consumer story was Wendy’s plan to introduce electronic menuboards in their restaurants that would allow them to implement “surge” pricing. In other words, to charge more during peak times.
Best we can tell this story was based on a financial presentation made to investors in early February during which the company’s CEO announced a $30-mil investment to deliver “significant restaurant margin expansion” by installing digital menuboards with “dynamic pricing & menu offerings:”
After a flood of news stories and negative consumer reaction to the prospect of having to pay more for the same food that was cheaper earlier in the day, Wendy’s issued a statement in its blog denying the plan.
*MOUSE PRINT:
To MrConsumer, the idea of a restaurant jacking-up its prices during peak times is just plain nasty. Will the items that are being surcharged be noted on the menuboard so customers know which ones they are?
And what about prices during off peak times? Will they be discounted below the current regular price? In other words, if a “Dave’s Single” burger is currently $4.99, will the peak price be, say, $5.99, but the off-peak price will be $3.99?
What do you think of the idea of a restaurant charging more during peak times?
A lawsuit was recently filed against Bank of America by a California consumer who claims the bank confiscated the cash rewards earned by her with her BofA credit card when the bank chose to close her account.
The consumer, Christy Ngo, says in the lawsuit that last September her debit card stopped working because the bank told her they had frozen her account and would close her checking and savings account by the end of the month. Preemptively, she withdrew all the money. How these account closings are related to her losing her accumulated credit card rewards is not explained in the lawsuit. We questioned her lawyers directly about that too, but they did not respond. And BofA declined to comment about the case to another media outlet.
For simplicity sake, let’s assume that the bank closed her credit card as well. Certainly the bank has a right to do that. But why didn’t they give her whatever amount of cash back she had already earned on her cards (assuming she had paid off her balance)?
*MOUSE PRINT:
The terms and conditions statement of BofA’s current “cash rewards” credit cards says that any unredeemed cash rewards at the time of closure, whether the closing was voluntary or not, would be forfeited.
Bank of America is not alone including fine print in their credit card agreements like this. Recently, after a TV reporter’s 98-year-old mother passed away, a California bank did the same thing. See story.
Most people don’t read the fine print of credit card agreements, and if they did, would any accountholder even remember this restriction perhaps years later? And is it fair for banks, even with proper disclosure, to confiscate already earned cash back that had not been redeemed rather than to automatically refund it?
Earlier this spring the Boston Red Sox announced a number of improvements to Fenway Park including that the venerable sport stadium was going cashless. That means if you want one of those famous Fenway franks or a beer or a souvenir you are going to have to pay with a credit or debit card.
Immediately MrConsumer knew that something was amiss here because Massachusetts law requires all retail establishments to accept cash.
*MOUSE PRINT:
No retail establishment offering goods and services for sale shall discriminate against a cash buyer by requiring the use of credit by a buyer in order to purchase such goods and services. All such retail establishments must accept legal tender when offered as payment by the buyer. — MGL c.255D, Sec. 10A
A number of states and cities have similar laws. It is often argued that the basis for this requirement is to prevent discrimination against the poor and minority groups that are more likely to be unbanked or underbanked. Despite the law, and apparently with only a cursory review, the Massachusetts Attorney General blessed this payment scheme after the Red Sox had already implemented it.
Federal law does not require the acceptance of cash irrespective of the “legal tender” language on our paper money.
At Fenway, three ReadyCARD kiosks have been installed to serve the one in 10 people who traditionally pay with cash. At these machines, those without a credit or debit card can insert cash ($5 minimum) and out pops a debit Mastercard. According to Red Sox management, there is no charge for the card. The card can then be used to pay for anything at the ballpark or anywhere else that Mastercard is accepted. The card is not refillable.
Demonstration of similar machine from the same company
MrConsumer suspected there were some hidden charges and other issues with these cards, but getting that information has proven almost impossible. Multiple requests to the Red Sox PR folks went unresponded to. Strike one. Multiple requests to Ready Credit Corporation, the provider of the reverse ATMs, also went unresponded to except for a terse statement advising us to contact the Red Sox because they themselves “don’t reply to media requests.” Strike two.
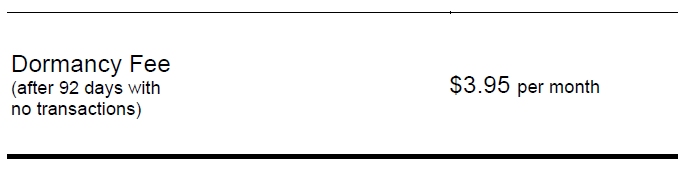
However, piecing together information gathered from Ready Credit’s website and one email from a Sox executive, prospective purchasers of these cards might be surprised to learn that there appears to be a $3.95 monthly “dormancy fee” automatically deducted from the card’s balance after just 92 days of non-use. [While Ready Credit would not confirm that this charge is from the applicable card agreement for the Fenway card, it appears to be.]
*MOUSE PRINT:
This is a big deal since you may not get full value for the cash you put on the card because of both the monthly fee and the general difficulty of using up small balances on any prepaid card.
Let’s say you have $8.12 left on the card and you want to buy a $10 item. Most online sellers don’t allow you to use a second debit or credit card to pay for the difference. (Amazon will allow you to transfer any remaining balance to your Amazon account, however.) Alternatively, you would have to find a retailer that will accept multiple forms of payment in one transaction known as a “split tender.” And if none of those options works for you, after a few months, don’t worry, the monthly fee will kick in, and the card’s balance will be wiped clean automatically in no time.
Under the Consumer Financial Protection Bureau’s (CFPB) relatively new rules, most vendors of prepaid cards have to disclose the costs of any card before purchase. It is unclear how reverse ATMs do this at Fenway Park, but the one above requires users to press an onscreen “terms and conditions” button to learn full details.
*MOUSE PRINT:
And even if you don’t click it, in fine print it says you have automatically agreed to the terms by buying a card or checking your balance.
Because of the unusual nature of these reverse ATM machines, and their location inside a private venue, the CFPB declined our request to confirm that the agency’s prepaid card rule actually applies in a case like this (although it probably does). And one of the most important provisions of that law prohibits card issuers from imposing a dormancy fee until the card has not been used for at least a year. Remember, this card charges a fee after just 92 days. Strike three.
So, we struck out in getting the full inside story about these cards. But, if you have used one of these machines at stadiums around the country, please tell us your experience in the comments below, and include if fees were disclosed to you prior to purchase.


 A