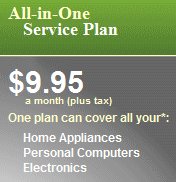
 From the folks who bring you FreeCreditReport.com, now there is Green Umbrella. It is an extended warranty plan for many household goods, and is sold by the month. Rather than buy a separate policy for each item, their plan is blanket coverage for multiple items in your house.
The company claims that “one plan can cover all your* Home Appliances, Personal Computers, and Electronics.”
Unless you just landed on planet earth (and didn’t bring anything with you from Mars), by its very terms, the plan cannot cover ALL items because:
*MOUSE PRINT:
“Covered Item means Electronics, Appliances, and Computers that meet the following requirements:
— Are purchased during the Coverage Period or within sixty (60) days prior to the Effective Date listed on the Cover Page of the Agreement; “
So, only items purchased no more than two months old are covered, as well as newly purchased items. The plan will not otherwise cover your existing computers, electronics, or appliances. [Note: Green Umbrella is running a promotion for September only whereby all qualifying items purchased during 2008 will be covered.]
How long does coverage last? As long as you pay the monthly fee, but you could fall into a trap. The coverage for any particular item is limited:
*MOUSE PRINT:
“Coverage begins on the date You purchase the Covered Item and terminates thirty-six (36) months from the purchase date”
You could easily be lulled into believing that your continued payments continue to cover everything purchased since the plan went into effect.
The service agreement is over 5500 words, and there are many catches and requirements, including having to register new purchases within 30 days; already purchased items must have come with at least a 12 month manufacturer’s warranty; if your DLP or LCD HDTV lamp burns out, they will only give you the bulb for you to replace on your own; you can only make two claims per year; and much more.
If you purchased the covered item with a credit card that provides extended warranty coverage, for say the second year, your coverage under this plan may be limited:
*MOUSE PRINT:
“Coverage is secondary to any other applicable warranty, insurance, indemnity, or extended warranty available to You. Coverage is limited to only those amounts not covered by any Other Coverage.”
So, if you have a manufacturer’s warranty for say a year, you must make a claim through it, and not this plan. The credit card warranty will kick in if you have a problem in the second year of ownership. And therefore only in year three will this plan provide any benefits. So you really have to do the math and recognize that your payments for the first two years of coverage cover nothing. In total, you will pay roughly $360 to get coverage in your products’ third year of life.
One last insult:
*MOUSE PRINT:
“The Coverage Period must continue without any lapse in payment (i.e. the Monthly Agreement Charge for this Agreement is not paid when due). If there is a lapse in payment a new Agreement will be issued upon receipt of the payment for the Monthly Agreement Charge. Only Electronics, Appliances, and Computers that qualify as Covered Items under the terms of the new Agreement will be covered.”
Translation: If your monthly payment arrives late, your old plan is cancelled and a new policy is issued. Therefore, all previously covered items will no longer be covered unless they were purchased in the prior two months.